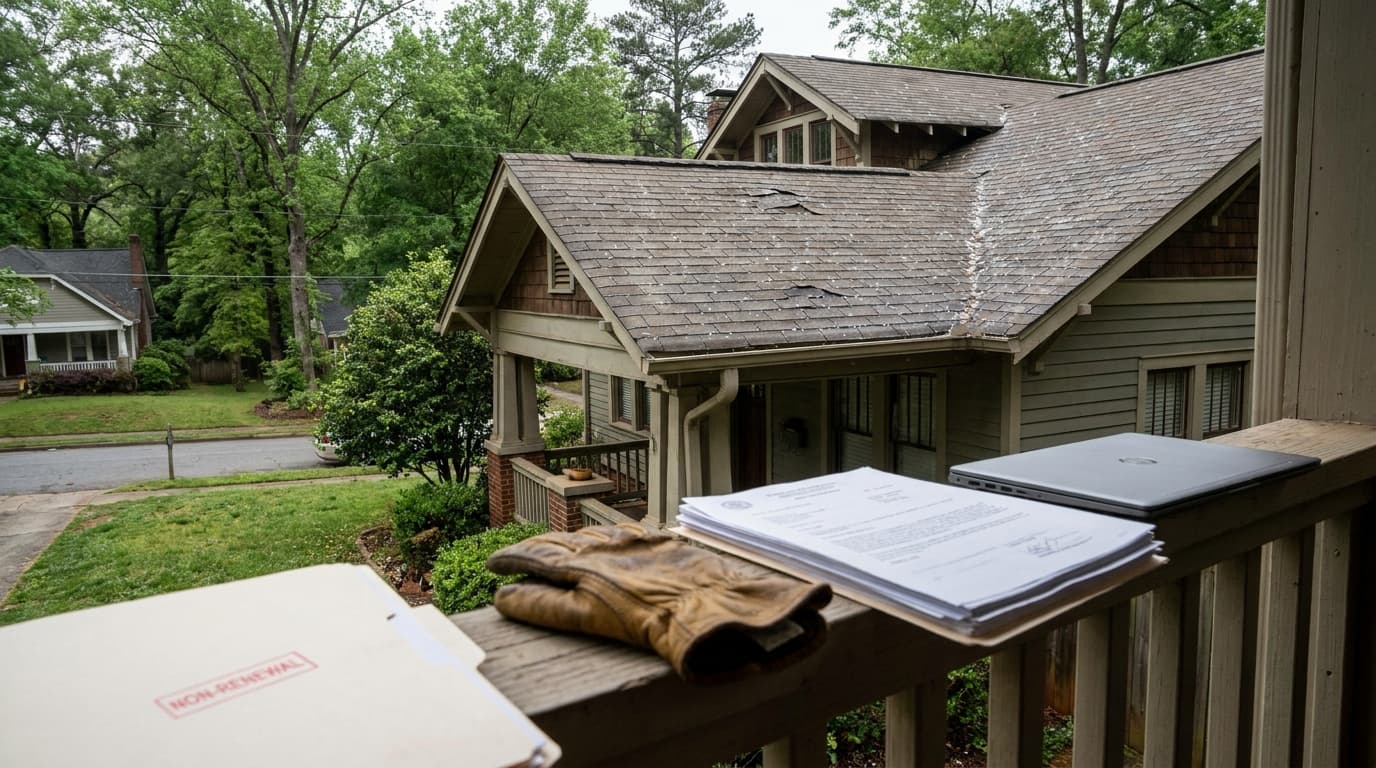
If you are buying a home in metro Atlanta's hail-prone exurbs — Henry, Paulding, Bartow, Cherokee, Carroll — the riskiest part of your closing in 2026 may not be the appraisal or the rate lock. It may be the homeowners insurance binder your lender pulls seven to ten days before funding.
Georgia homeowners premiums are projected to climb roughly 10% statewide in 2026, on top of an 8.6% increase in 2025 and a cumulative 39.7% run-up since 2021. Insurance Commissioner John F. King has attributed the trend to inflation, labor and materials costs, and damage from Hurricane Helene. None of that is news to anyone who has opened a renewal notice in the last two years. What is changing is where the squeeze is landing. The kind of underwriting tightening once associated with coastal Georgia is now showing up in the inland hail belt, and it is starting to collide with the mortgage process in ways borrowers do not see coming.
This article walks through what is actually verified about the 2026 rate environment, how carriers use claim history to non-renew, what Georgia statute and federal rules require when that happens, and — most importantly — what it does to a mortgage that is already in underwriting.
What is actually changing in 2026
It is worth separating the signal from the noise here, because the headlines run ahead of the filings.
The verified macro picture: Insurify projects a roughly 10% statewide premium increase for 2026, the third consecutive year of meaningful hikes. Atlanta-area homeowners already pay materially more than the state average — NerdWallet's 2026 analysis puts the Atlanta average around $3,420 a year against a statewide average closer to $2,640. The Office of Commissioner of Insurance and Safety Fire publishes individual carrier filings on its regulatory filings portal, and that is the only authoritative place to confirm any specific carrier rate change before treating it as fact.
A useful data point on that front: State Farm's most recent publicly reported Georgia filing, in November 2025, was a rate decrease of roughly 3% — not an increase. That does not mean the broader market is softening. Smaller and regional carriers continue to file double-digit hikes, and the loss-ratio analysis published in Insurance Journal suggests that pressure is still building, particularly outside the largest national writers. The point is that the carrier-by-carrier picture is uneven, and a buyer should not assume their renewal will look like the average.
Why exurbs are the new front
Metro Atlanta sits in one of the more active hail corridors east of the Mississippi. RestoreMasters' compilation of Georgia hail data notes that Henry County alone was hit by one of the state's most damaging hailstorms back in 2013, and metro hail exposure has been a recognized rate driver across carriers ever since.
Layer on top of that a decade of exurban tract construction. Newer subdivisions in Paulding and Bartow tend to feature larger roof footprints, attached garages, and asphalt-shingle roofs that age into the claims zone all at once. Reconstruction costs are higher than they were pre-pandemic, and reinsurance — the coverage carriers buy to protect themselves against catastrophe years — has gotten meaningfully more expensive. Allstate, for example, disclosed roughly $925 million in pretax March 2026 catastrophe losses from 15 wind and hail events; the storm corridor in that disclosure ran from Texas and Oklahoma through Tennessee and the Mid-Atlantic, not primarily Georgia, but it illustrates how a single bad month can reshape an entire region's underwriting posture.
How carriers actually decide to non-renew
Industry practice on claim-frequency non-renewal is not uniform, and it is worth being precise. The Zebra's overview describes a common industry shorthand of "three claims in three years" as a typical threshold beyond which carriers may decline to renew, though the specific rules vary by carrier, by state, and by the type of claim (weather versus liability versus theft). Hail and wind claims tend to weigh more heavily in catastrophe-exposed counties.
If you are shopping in a hail-prone exurb, the practical implication is straightforward: a roof that has filed two or more weather claims in the recent past is a flag that a new buyer will inherit. The seller's claim history travels with the property in the form of the carrier's underwriting view of the address, and a CLUE report (the industry's claims database) is something a good independent agent will pull before quoting.
The closing-table mechanics
Here is where insurance pressure meets the mortgage. Lenders require continuous hazard coverage from day one of ownership through payoff. Most loans escrow that premium. In a typical purchase timeline, the underwriter pulls a homeowner's binder seven to ten days before closing, and a Closing Disclosure goes out at least three business days before the funding date.
If your binder falls through inside that window — because the carrier you bound with non-renewed the address, the rate came in dramatically higher than disclosed, or the policy was conditional and a re-inspection killed it — several things can happen at once. The Loan Estimate's escrow projection may no longer match reality, which can trigger redisclosure and reset the three-day clock. A higher premium can move your debt-to-income ratio out of program tolerance. The lock may need to be extended at cost. In a fast-moving file, that is often the difference between closing on time and not closing at all.
What Georgia statute requires when you are non-renewed
Carriers in Georgia do not get to drop a residential property policy on no notice. O.C.G.A. § 33-24-46 requires at least 30 days' written notice of cancellation or non-renewal for most residential property policies. O.C.G.A. § 33-24-47 extends that to 45 days when the premium is going to increase by more than 15% — a category of "effective non-renewal" that catches a lot of borrowers off guard, because the policy renews but at a rate they did not budget for.
The OCI's Bulletin 24-EX-2 spells out what carriers may and may not do when non-renewing residential coverage. If you receive a non-renewal notice, ask in writing for the reason code. Carriers are expected to provide one, and the reason matters: a non-renewal based on roof age can be cured by a new roof; one based on claim frequency cannot be cured at all and will follow the address.
Force-placed insurance — and why you should fight to avoid it
If your coverage lapses after closing and the servicer cannot confirm replacement coverage, federal Regulation X kicks in. Under 12 CFR 1024.37, a servicer must send an initial notice at least 45 days before charging you for force-placed (also called lender-placed) insurance, plus a reminder at least 15 days before charging — and the reminder cannot go out earlier than 30 days after the first notice. If you provide proof of acceptable coverage at any point, the servicer must terminate the force-placed policy and refund any overlapping premium.
Force-placed coverage is materially more expensive than what you would buy on the open market, and it protects the lender's interest in the property — not yours. There is generally no liability coverage, no personal property coverage, no loss-of-use. Fannie Mae's Servicing Guide B-6-01 sets the conforming-loan rules for how servicers must handle force-placed coverage, including the requirement to accept compliant borrower-obtained coverage when presented. The CFPB's consumer guidance walks through the borrower's rights step by step.
The practical takeaway: if you are non-renewed mid-loan, do not let the clock run out. Force-placed premium gets added to escrow, raises your monthly payment, and — if you are also in the middle of a refinance or sale — can sink the file.
What this does to your DTI
Homeowners insurance is part of PITI — principal, interest, taxes, insurance — and PITI feeds the front-end housing expense ratio that underwriters use to qualify you. Fannie Mae's Selling Guide B3-6-02 lays out the conventional-loan calculation. Conventional loans through the automated underwriting systems typically cap total DTI in the 43% to 45% range (sometimes higher with strong compensating factors). FHA generally targets 31% front-end and 43% back-end before overlays. VA does not have a hard DTI cap but uses residual income as a backstop.
The math is unforgiving. Take a borrower qualifying at a 41% back-end DTI with a $2,800 PITI on a $475,000 purchase. If insurance comes in $300 a month higher than the original quote — entirely plausible if a force-placed or surplus-lines policy replaces a standard-market quote — that PITI jumps to $3,100. On a $7,000 monthly income, the back-end ratio moves from 41% toward the 45% ceiling. On a thinner file, it can break the loan.
This is why a non-renewal letter that arrives three weeks before closing is not just an insurance problem. It is a loan problem.
The playbook if you get dropped before closing
-
Get the non-renewal in writing with a reason code. § 33-24-47 entitles you to it. Without the reason code you cannot shop intelligently.
-
Call an independent agent, not a captive. Independent agents quote multiple admitted carriers in one call; captives quote one. In a tight window, breadth matters.
-
Try the admitted market first. Admitted carriers are regulated by Georgia OCI, are backed by the Georgia Insurers Insolvency Pool, and produce policies your lender will accept without friction.
-
Consider surplus lines as a bridge, not a destination. Surplus lines (non-admitted) carriers under O.C.G.A. Title 33, Chapter 5 will write risks the admitted market rejects. Premiums run higher than the admitted market, coverage forms vary, and these policies are not backed by the state guaranty fund. They can get you to the closing table, but plan to re-shop annually.
-
Know that the Georgia Underwriting Association is the backstop. Established under O.C.G.A. § 33-33-1, the GUA — the state's FAIR Plan — is the insurer of last resort. Coverage is narrower than standard policies and premiums are higher, but lenders accept GUA policies because the pool is statutorily created.
-
Talk to your lender about extension or re-lock options. If a binder is going to be three days late and an extension fee is the difference between closing and starting over, take the extension fee.
-
Document everything. Keep copies of every quote, every declination, every binder. If you end up in force-placed coverage, that paper trail is what gets you refunded under 12 CFR 1024.37.
The CFPB's consumer advisory on cancellations and cost surges walks through the federal-side options if escalation is needed.
What to do before you buy in a hail-prone exurb
Most of this is decided before contract, not after.
-
Verify roof age and material during due diligence. A 12-year-old three-tab roof in Paulding is a different insurance risk than a 3-year-old architectural shingle, and a different risk again from impact-resistant (Class 4) shingles, which often qualify for a premium credit.
-
Pull a CLUE report on the property. Your agent can order one. A history of two weather claims in five years will follow the address, and you want to know before you write an offer.
-
Quote the policy before binding your rate lock. Get a real quote from an independent agent — not a rough estimate — before you lock. A $3,400 Atlanta-average premium and a $5,800 hail-belt premium are different DTI calculations.
-
Pay attention to wind/hail deductibles. Many Georgia policies now carry a separate wind/hail deductible expressed as a percentage of dwelling coverage — often 1% to 2%. On a $400,000 dwelling, that is $4,000 to $8,000 out of pocket on the next storm.
-
Shop beyond the four big carriers. Regional and specialty admitted carriers sometimes price hail-belt risks more rationally than the national names. An independent agent will know who is currently writing in your ZIP.
Looking ahead
2026 is also a commissioner election year. The Atlanta Journal-Constitution has reported on the affordability messaging that is shaping the race, and the OCI's posture on non-renewals — articulated in Bulletin 24-EX-2 — is likely to remain a live issue. For borrowers, the practical horizon is shorter: the next renewal cycle, the next storm season, the next binder.
If you are closing in the next 90 days, treat the homeowner's binder as a critical path item, not a checklist box. Get the quote in writing early, shop independent, and budget for a premium higher than the headline average. The mortgage will close. It just needs the insurance to hold.
Related reading
Sources
-
WABE / Grist — Are Georgia and other states becoming uninsurable?
-
Live Insurance News — Georgia Home Insurance Rates Are Rising Faster Than the National Average
-
Repairer Driven News — State Farm files insurance rate reductions in GA and CA
-
Georgia OCI Bulletin 24-EX-2 — Nonrenewal Requirements and Prohibitions
-
O.C.G.A. § 33-24-46 — Cancellation or nonrenewal of property insurance policies
-
O.C.G.A. § 33-24-47 — Notice required of termination, nonrenewal, or premium increase
-
O.C.G.A. § 33-33-1 — Georgia Underwriting Association (FAIR Plan)
-
Live Insurance News — Allstate's $925M March 2026 storm losses
-
Insurance Journal — Recommendations on Georgia's Rising Premiums and Loss Ratios
This article is general information, not insurance, legal, or mortgage advice. Confirm any rate change, statutory requirement, or loan program rule with a Georgia-licensed independent insurance agent and a licensed Georgia mortgage professional before acting.


