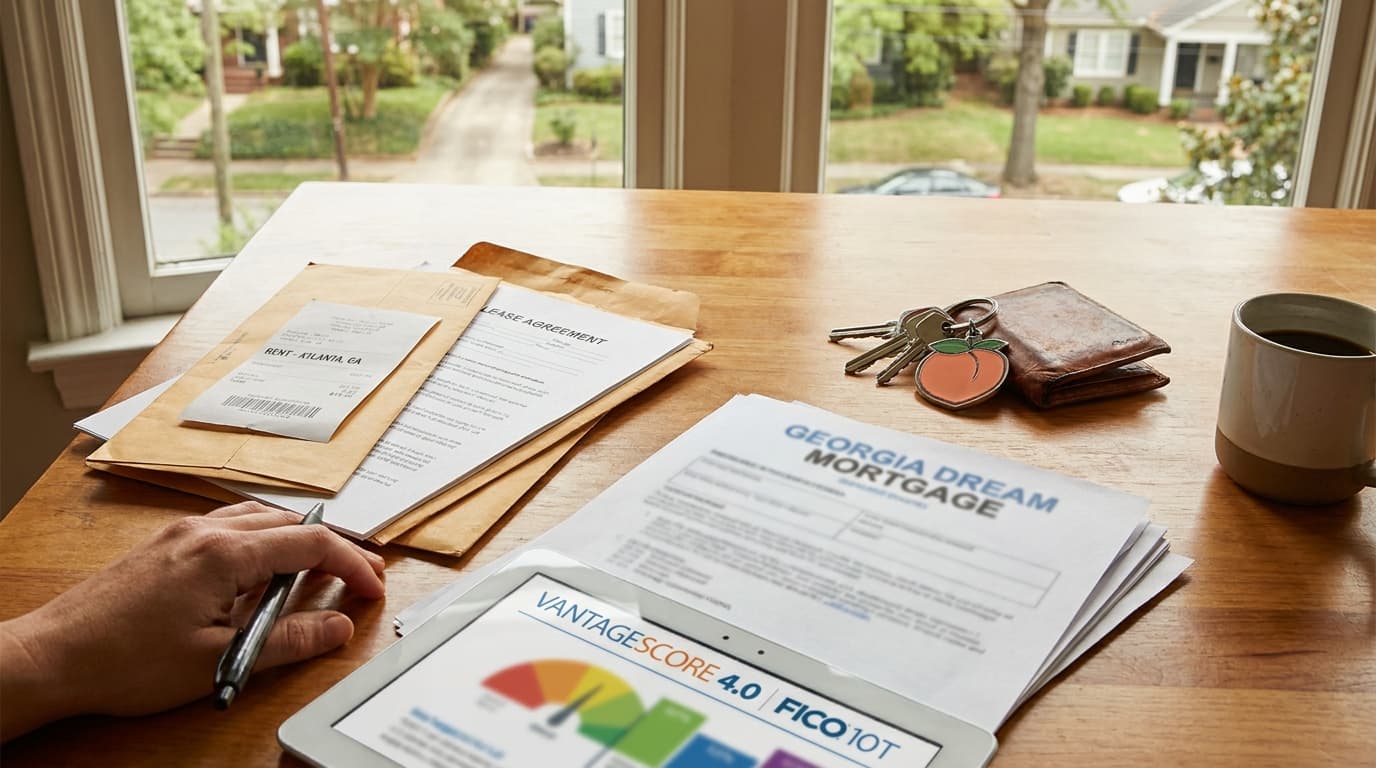
If you rent an apartment in metro Atlanta, pay your $1,400 a month on time every month, and have watched that perfect track record do absolutely nothing for your mortgage application, something changed on April 22, 2026. On that day, the director of the Federal Housing Finance Agency (FHFA) and the Secretary of Housing and Urban Development (HUD) jointly announced that Fannie Mae, Freddie Mac, and FHA will accept two newer credit-scoring models — VantageScore 4.0 and FICO 10T — alongside the Classic FICO model that has governed mortgage underwriting for decades. The reason a careful Georgia renter should pay attention: these newer models can read on-time rent payments and two years of credit behavior that the old model simply ignored.
That is the genuinely good news. The honest news, which matters just as much, is that this is a partial, uneven rollout — not an overnight fix. Below is what actually changed, who stands to benefit, and what a thin-file first-time buyer in Georgia should realistically do about it.
What was approved — and what that does and doesn't mean for you
The April 22 action did two distinct things. First, it confirmed that VantageScore 4.0 is usable now on conventional loans backed by Fannie Mae and Freddie Mac — but only through a limited set of approved lenders, not across the whole industry. Second, it added FHA into the picture and formally opened a track for FICO 10T, a competing newer model.
It is worth separating two ideas that are easy to blur together: a model being approved by the GSEs is not the same as that model being available to you at your particular lender today. Approval is the regulatory green light. Availability depends on whether the specific lender you walk into has implemented the new model in its underwriting. Right now, many have not.
FICO 10T is the clearest example of "approved but wait." Fannie Mae and Freddie Mac plan to publish historical FICO 10T score data — covering loans acquired roughly between April 2013 and September 2025 — in summer 2026 to support broad adoption. Until lenders and investors have that historical data to price against, FICO 10T's everyday use stays limited.
Why this is genuinely the first new mortgage credit score in a generation
This is not a tweak. The Classic FICO model has been the GSE standard for decades, and changing it has been talked about for years without much happening. FHFA originally validated both VantageScore 4.0 and FICO 10T back in October 2022, then the implementation was repeatedly delayed. The first real movement came on July 8, 2025, when FHFA announced immediate acceptance of VantageScore 4.0 for GSE loans. The April 22, 2026 announcement broadened that — adding FHA and the FICO 10T track on top.
So when you see this described as the first major shift in GSE-accepted mortgage credit scoring in decades, that framing is fair. For Georgia buyers, the practical question is simply whether the change reaches your loan file in time to matter.
How rent and "trended data" actually help
The core mechanical difference is this: Classic FICO looks at your credit as a single-point-in-time snapshot. VantageScore 4.0 and FICO 10T use trended data — up to 24 months of credit behavior — so the direction you are moving in matters, not just where you stand today.
On top of that, VantageScore 4.0 can incorporate alternative data, including on-time rent and utility payment history. This is the part that speaks directly to Atlanta renters. But read the condition carefully: rent only counts when it is actually reported through a rental or data-furnishing service. It is not automatic. If your landlord or property manager doesn't report your payments, and you haven't enrolled in a rent-reporting service that does, those payments still won't show up in your file.
Why does this matter so much in Georgia specifically? Because metro Atlanta rents are substantial. Recent 2026 figures put the average one-bedroom around $1,225 and the median two-bedroom near $1,820, with many renters paying somewhere in the roughly $1,200 to $1,800-plus range each month. That is a large, recurring, on-time payment history that — under the old model — did nothing for a mortgage application. VantageScore says its 4.0 model scores roughly 33 million more people than legacy models, largely by not requiring recent traditional credit activity. That is the thin-file population: people who pay their bills but lack a thick stack of credit cards and installment loans.
The winners — and who doesn't win as much
Trended data is not uniformly good news for everyone. Because the model now sees 24 months of behavior, it tends to reward borrowers who have visibly paid balances down and can quietly disadvantage borrowers who carry high revolving balances — even two people sitting at the same current score.
A concrete example helps. Imagine two borrowers who both show a similar score today. One has steadily paid a credit card down from about 75% utilization to 30% over the past two years. The other has hovered at high utilization the whole time, paying interest but never really reducing the balance. Under a single-point snapshot, they can look alike. Under trended data, the borrower trending downward looks meaningfully stronger, because the model can see the trajectory. If you are carrying balances and hoping the new model rescues your file, it may not — and in some cases the fuller picture works against you.
The reality check on availability
This is where measured expectations matter most. VantageScore 4.0 is live on conventional loans, but only at a limited set of approved lenders — trade reporting describes the lender rollout as partial and still ramping. FICO 10T's broad use waits on that summer-2026 historical-data publication. So the practical move is not to assume the new scoring will be applied to your loan; it is to ask.
When you talk to a Georgia lender, ask plainly: "Which credit model do you pull for the loan I'm applying for — Classic FICO, VantageScore 4.0, or FICO 10T? And if rent reporting could help my file, do you accept it?" The answer will vary by lender today, and that is exactly why asking is worth your time.
Why the score in your credit app won't match the one your lender pulls
Here is a common and avoidable disappointment. The VantageScore you see in a free consumer credit app is generally not the mortgage-specific VantageScore 4.0 that a lender pulls for underwriting. Don't expect the numbers to line up. A free app score is a useful directional gauge of your credit health, but it is not the figure a mortgage underwriter will use. If you walk in expecting the app number and get a different one, that is the model difference at work, not an error.
The cost question, framed honestly
You may have seen a figure floating around that the change could save "about $100 per loan." Be careful with that one. Officials have framed the savings as over $1 billion in aggregate first-year savings for consumers and lenders combined — an industry-wide number. The widely-repeated per-loan figure is an estimate extrapolated from that aggregate, not a guaranteed discount any individual borrower is promised. The accurate takeaway: there may be system-wide efficiency and savings, but you should not bank on a specific dollar figure showing up on your own closing statement.
Georgia action steps
If you are a Georgia renter eyeing a first home, here is how to actually use this change:
-
Get your rent reported. The benefit only materializes if your on-time rent flows into your credit file through a rental-reporting or data-furnishing service. Ask your property manager whether they report payments, and look into rent-reporting services if they don't. Without reporting, the new model can't count what it can't see.
-
Pay balances down before you apply. Because trended data rewards a visible downward trajectory on revolving debt, the months before you apply are a good time to chip away at card balances rather than let them ride.
-
Stack it with down-payment help. The credit-model change affects qualification and scoring — it does not provide down-payment money. But it pairs naturally with existing Georgia assistance. The Georgia Dream program offers down-payment assistance in the range of roughly $10,000 to $12,500, and the City of Atlanta has down-payment assistance reaching up to $20,000. The new scoring may help you qualify; these programs help with the cash to close.
-
Interview your lender on credit models. Ask which model they pull, whether they're among the approved VantageScore 4.0 lenders, and whether rent data can be factored in. If one lender can't use the newer model yet, another may.
Bottom line
For thin-file, first-time buyers in Atlanta and across Georgia, this is a real structural opening — the first time in decades that a spotless rent history and two years of responsible credit behavior can actually count toward a mortgage. That deserves to be taken seriously. But it is a partial rollout: VantageScore 4.0 is live only at a limited set of lenders, FICO 10T's broad use waits on summer-2026 data, rent only helps if it's reported, the benefit skews toward people paying balances down, and the savings are an aggregate figure, not a personal guarantee. Treat it as a door that has opened, not a fix that has arrived — and walk through it deliberately.
This article contains AI-assisted content and has been reviewed in our publication workflow.
Related reading
-
[Georgia Dream's Late-2025 Reset: Why Atlanta First-Timers Who Missed the Cutoff Should Run the Numbers Again](/article/georgia-dream-2026-reset-atlanta-first-time-buyers)
-
The Refi Window Just Cracked Open for Georgia's 2023–2024 Borrowers — Here's the Break-Even Math
Sources
-
FHFA — Homebuying Advances into New Era of Credit Score Competition
-
VantageScore — FHFA Director and HUD Secretary Jointly Announce VantageScore 4.0 Implementation
-
ABA Banking Journal — HUD, FHFA roll out plans for new credit scoring in mortgages
-
Better — New mortgage credit score models in 2026: VantageScore 4.0 and FICO 10T
-
Scotsman Guide — Lenders begin rolling out VantageScore for Fannie Mae and Freddie Mac loans
-
Rent.com — Rental Market Trends & Average Rent in Atlanta, GA
-
[LendingTree — Georgia First-Time Homebuyer Programs in 2026](https://www.lendingtree.com/home/mortgage/georgia-first-time-homebuyer-programs/)